Insurance tied to a loan: life, DASK, home insurance and kasko
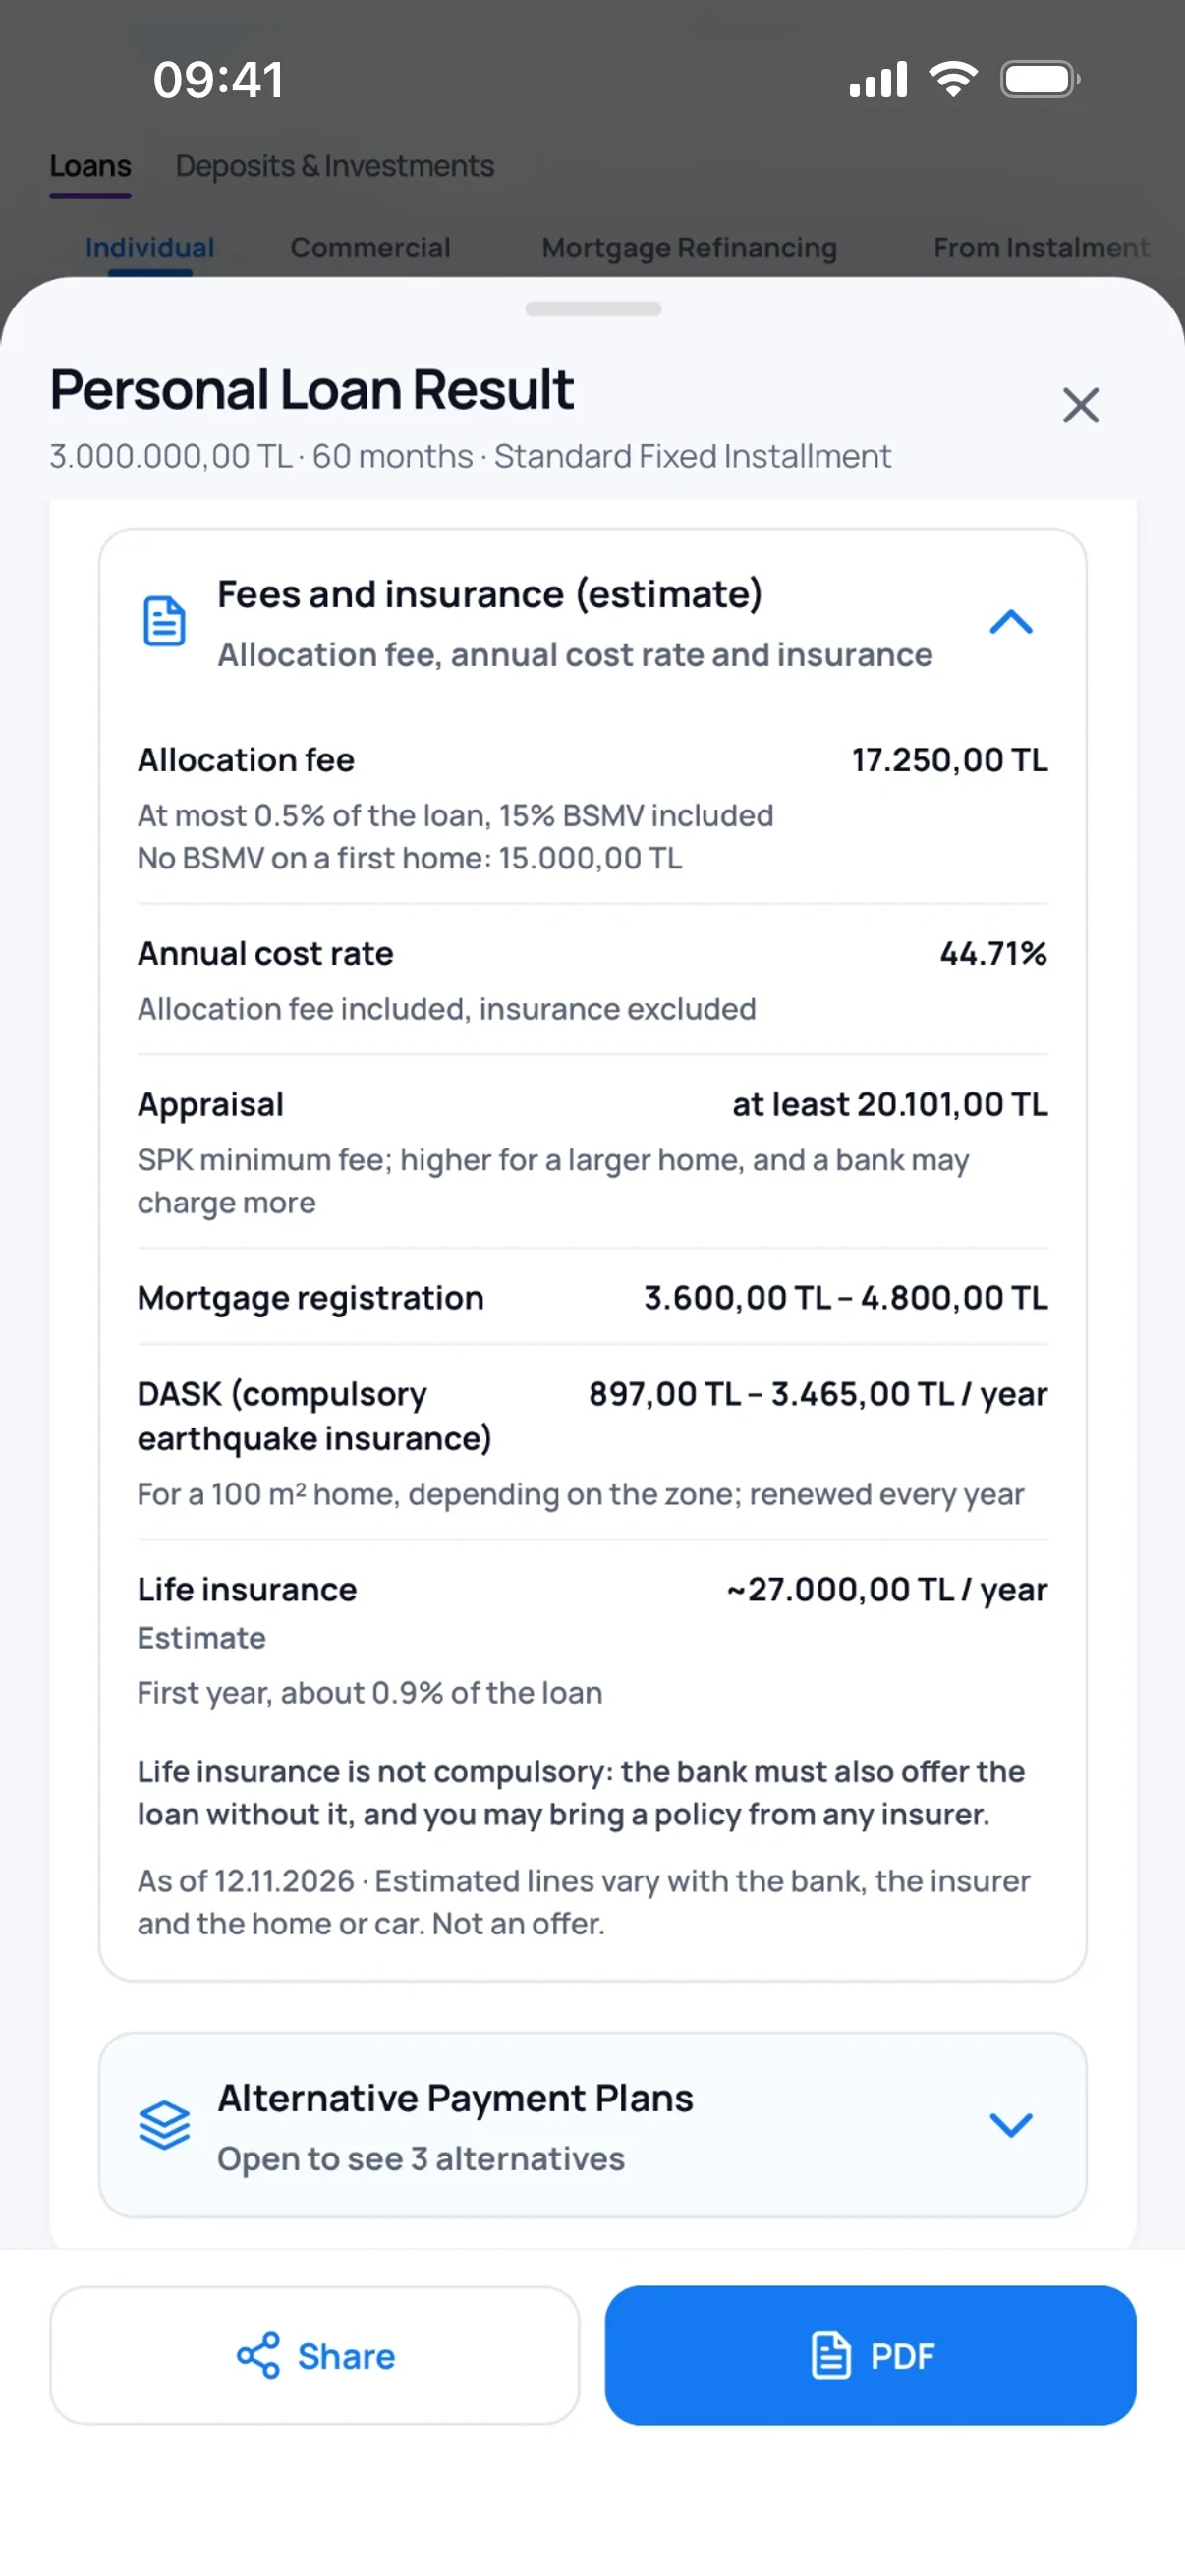
On a consumer loan, life insurance, home insurance and kasko are credit-linked insurance: they cannot be taken out without your explicit request, and the bank must also offer a deal without them. If you bring a policy from another insurer that matches the loan's amount and term, the bank accepts it without changing the loan's terms. The only insurance the law makes compulsory is DASK on a home.
Updated: 16 November 2026. Rules as read on 12 November 2026.
This page is general information. Premiums depend on age, the loan and the insurer; the figures here are published examples, not quotes.
The rule: an explicit request and your choice of insurer
Articles 29 (consumer loans) and 38 (housing) of Law 6502 have said since 24 March 2022 that credit-linked insurance cannot be taken out without your explicit request in writing or on a durable medium, and that the bank must also offer the contract without insurance.
You may insure with any company. A policy that matches the loan's amount and term and names the bank as loss payee is accepted with no change to the offered loan terms (Regulation on Consumer Credit Contracts art. 26/3; for housing, Regulation on Housing Finance Contracts art. 10). So bringing your own policy keeps the insured rate.
Since 1 January 2023 the insured and uninsured repayment plans are shown side by side on a preference form. More than one policy for the same cover, or cover above the loan amount, is not allowed.
What life insurance costs
Insurers publish no credit life tariff; the firmest figures are the examples on banks' product pages. The cover falls with the remaining debt.
| Loan | Age | Premium, share of the loan |
|---|---|---|
| Personal, 100,000 TL, 12–36 months | 35 | 3.6–3.8% |
| Personal, with unemployment cover, 100,000 TL, 12 months | 35 | 5.6% |
| Housing, 1,000,000 TL, 120 months | 35 | 0.9% in year one |
Footnote examples on banks' own product pages, November 2026. A term life product not tied to a loan costs about a half to a third as much for the same cover; whether a bank accepts a policy whose cover does not fall depends on the bank.
DASK (compulsory earthquake insurance)
Every unit used as a home must carry DASK; the owner takes it out and renews it every year (Law 6305, art. 10). The land registry does no transaction without a valid policy. A bank checks DASK when it pays out a loan, and if there is none it tells you, charges you the premium and takes it out itself.
The premium is a per mille rate of the insured value. The insured value is the floor area times a unit value that rises every month by the previous month's producer price change.
| Risk group | I | II | III | IV | V | VI | VII |
|---|---|---|---|---|---|---|---|
| Reinforced concrete, per mille | 2.82 | 2.51 | 2.13 | 2.00 | 1.50 | 1.07 | 0.73 |
| Minimum premium, TL | 2,426 | 2,159 | 1,832 | 1,721 | 1,290 | 920 | 628 |
Example: a 100 m² reinforced concrete home in November 2026. The unit value is 12,288 TL/m² and the insured value 1,228,800 TL; the premium is 3,465 TL in group I and 897 TL in group VII. The deductible is 2% of the insured value per claim.
Home insurance
Home (fire) insurance is not compulsory; it is credit-linked insurance, so the explicit request, the uninsured offer and the choice of insurer apply here too. The insured value is the cost of rebuilding, land excluded. Banks may price insured and uninsured offers differently.
Kasko and traffic insurance on a vehicle loan
Kasko on the financed car is credit-linked insurance and may come from another insurer. In a claim the payout goes first to what the bank is owed. Compulsory traffic insurance is a cost of owning the car, not of the loan; the regulator sets its maximum premium every month.
Insurance on a business loan
A business loan has no consumer protection and no required uninsured offer. Your choice of insurer still cannot be limited; a contract clause requiring a named company is void (Insurance Law 5684, art. 32/5). The Credit Guarantee Fund is a guarantee, not insurance.
Withdrawal, switching and refunds
| Situation | Time | Result |
|---|---|---|
| Bringing another suitable policy instead of the bank's | First month | The bank's policy is cancelled from the start; the premium comes back in full within 5 business days |
| The same, after the first month | – | A refund by days, or the surrender value |
| Withdrawing from credit life insurance | 15 days from notice | Premium refunded |
| Withdrawing from the loan contract | 14 days | The insurance sold with it ends too |
When a loan is closed early, its life insurance ends and the rest of the premium is refunded; it can go on with your explicit consent. Kasko and home insurance do not end by themselves on early repayment; if you cancel them you get a refund by days or the surrender value.
Insurance and the annual cost rate
Banks leave the premium out of the annual cost rate. When you compare an insured and an uninsured offer, add the insured offer's premium to its instalments yourself; a lower insured rate can cost more than the uninsured one once the premium is in.
12 November 2026: the regulation on embedded insurance
For life, payment protection and personal accident insurance tied to personal loans that banks give on e-commerce sites, the yearly gross premium may not exceed the monthly gross minimum wage of the year's first half, and cover runs at most two years (art. 5/1-d, art. 7).
You can run this with your own figures in the Bankacı app and the member portal.
Retail loans: personal, vehicle and housing loan calculation →Housing loan calculation →Vehicle loan calculation →Download the app ↗Member portal ↗
Frequently asked
Is life insurance required for a loan?
Not on a consumer loan. It needs your explicit request, and the bank must also make an offer without it. Insured loans usually get a lower rate; count the premium when you compare.
Can I insure outside the bank?
Yes. The bank must accept, with no change to the loan's terms, a policy that matches the loan's amount and term and names the bank as loss payee.
If I drop the bank's insurance, do I get the premium back?
If you bring another suitable policy within the first month, the bank's policy is cancelled from the start and the premium comes back in full within five business days. Later, you get a refund by days or the surrender value.
What if I don't take out DASK?
DASK is compulsory on a home and the land registry does no transaction without it. On a housing loan, if there is none, the bank tells you, charges you the premium and takes it out itself.
Sources
- Law 6502 on Consumer Protection, art. 24, art. 29 and art. 38, read on 12.11.2026: mevzuat.gov.tr
- Regulation on Consumer Credit Contracts, art. 26, read on 12.11.2026
- Regulation on Housing Finance Contracts, art. 10, read on 12.11.2026
- Regulation on the Principles of Insurance Linked to Personal Loans, art. 10, art. 11 and art. 14, read on 12.11.2026
- Insurance and Private Pension Regulation and Supervision Agency, circular 2022/5 and notice 2025/2, 5.3.2025
- Law 6305 on Disaster Insurance, art. 10 and art. 11; the DASK tariff, 1.1.2026; unit value 1.11.2026
- Insurance Law 5684, art. 32/5, read on 12.11.2026
- Regulation on Embedded Insurance, art. 5 and art. 7, 12.11.2026
This page is general information. Premiums depend on age, the loan and the insurer; the figures here are published examples, not quotes.
Be ready for your next calculation.
Download Bankacı for free.
 Scan with your phonebankaci.app/indir