Loan fees in Turkey 2026: allocation fee, appraisal and taxes
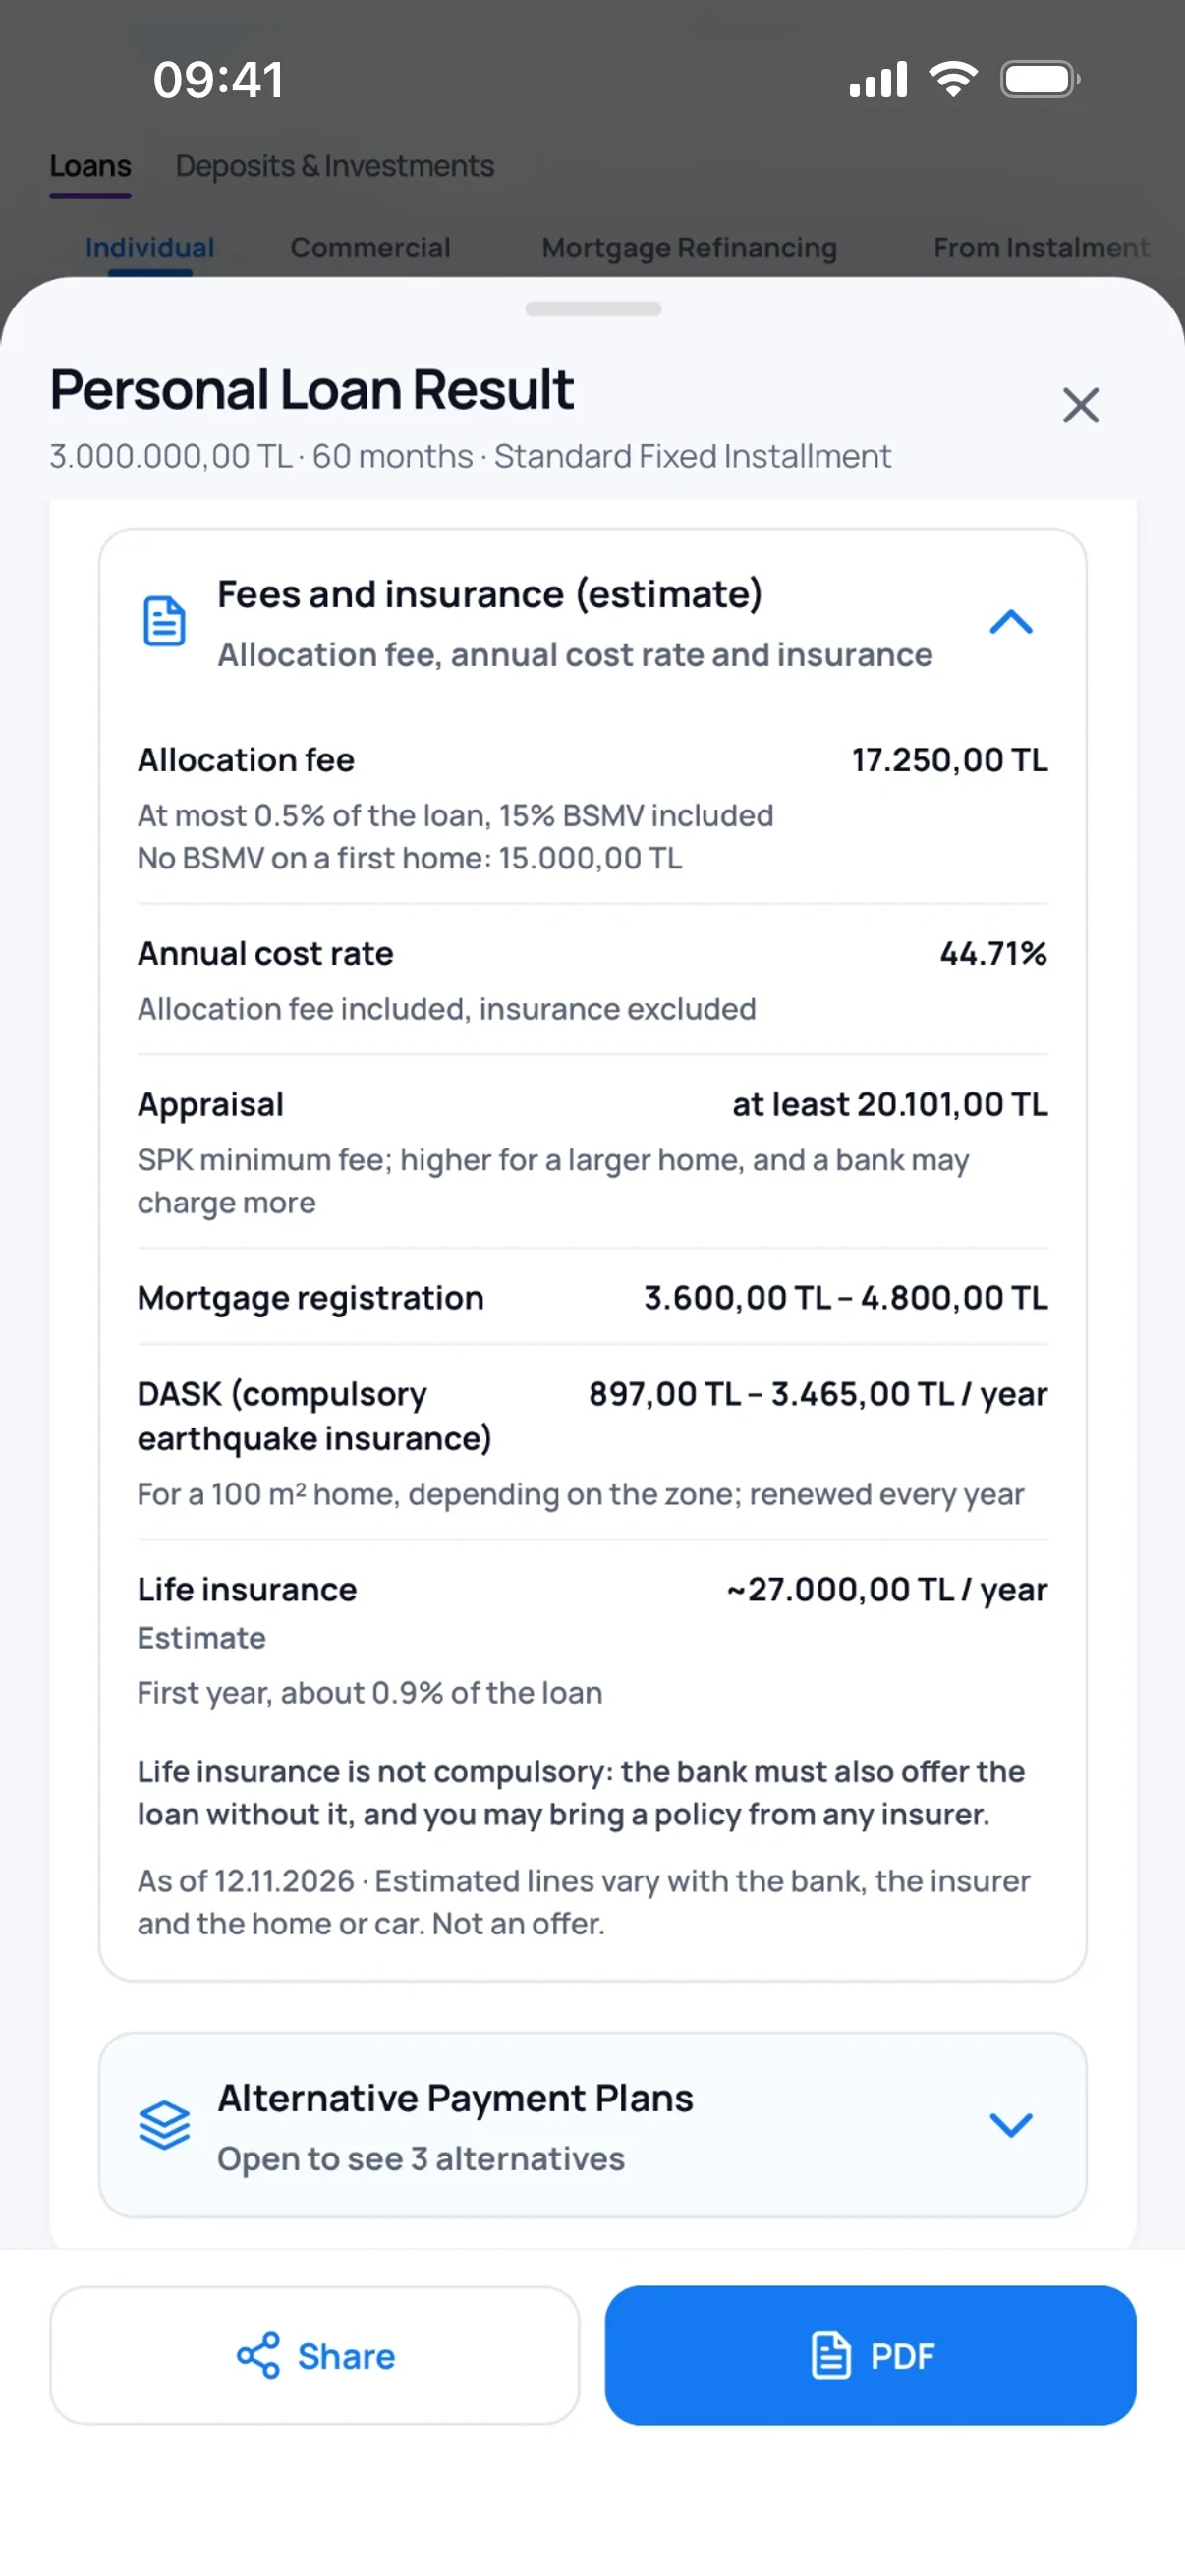
Besides interest, a loan costs the bank's fees and the state's levies. On a consumer loan a bank may charge only an allocation fee: at most 0.5% of the principal, with 15% BSMV on top, which comes to 575 TL on 100,000 TL. On a business loan the allocation and drawdown fees are separate, and both have had a ceiling in the central bank's communiqué since 1 November 2025. For appraisal, mortgage and pledge a bank may pass on only what it pays to others.
Updated: 16 November 2026. Rules as read on 12 November 2026.
This page is general information. The amounts your bank charges are in your contract and in the fee calculator on the bank's site; this page shows only the legal ceilings and examples.
The allocation fee on a consumer loan
For personal, vehicle and housing loans the rule is the Turkish central bank's communiqué on fees charged to financial consumers (2020/7). A bank may charge one fee for a loan, the allocation fee. Nothing may be charged as an inquiry, file, transaction or plan-change fee, and a refused application costs nothing.
The allocation fee may not exceed 0.5% of the principal paid out. BSMV is not part of that ceiling; it is added on top at 15%. On a housing loan to someone with no other home in their name there is no BSMV, and the fee stays at 0.5%.
| Loan | Allocation fee ceiling | On 100,000 TL |
|---|---|---|
| Personal and vehicle | 0.5% + 15% BSMV | 575 TL |
| Housing, first home | 0.5%, no BSMV | 500 TL |
| Housing, owner of another home | 0.5% + 15% BSMV | 575 TL |
Banks have to offer a calculator on their sites that shows these fees.
Appraisal, mortgage and pledge
Here a bank may pass on only what it pays to third parties and the state; the central bank sets no TL ceiling. A home appraisal starts from the Capital Markets Board's 2026 minimum fee schedule. No discount is allowed, and 20% VAT, a 176 TL real estate information centre share and a 125 TL union share come on top.
| Home size | Minimum fee | With VAT and shares |
|---|---|---|
| Up to 149 m² | 16,500 TL | 20,101 TL |
| 150–250 m² | 17,622 TL | 21,447 TL |
| 251–500 m² | 20,217 TL | 24,561 TL |
| 501–1,000 m² | 23,946 TL | 29,036 TL |
Bank loans pay no stamp duty and no mortgage fee. The land registry charges only its service fee for the mortgage. A vehicle pledge is set up at a notary, with no fee to the state.
Allocation and drawdown fees on a business loan
The rule is the central bank's communiqué on fees charged to commercial customers (2020/4). After the change of 18 September 2025, two ceilings apply from 1 November 2025.
The allocation fee is at most 0.20% of the limit. It is charged yearly and prorated by the months the limit runs; when a limit grows, only the added part is charged.
The drawdown fee applies only to cash loans and is at most 1.10% of the amount paid out. On a revolving loan it is charged yearly on the average balance, and it falls by days for a term under a year. Since 1 February 2026 this ceiling applies only to TL cash loans.
| 1,000,000 TL, 12 months, TL cash | Ceiling | With 5% BSMV |
|---|---|---|
| Allocation fee | 2,000 TL | 2,100 TL |
| Drawdown fee | 11,000 TL | 11,550 TL |
Taxes
On a consumer loan the interest carries 15% KKDF and 15% BSMV; the fee carries only 15% BSMV.
| Item | Personal, vehicle | Housing | Business |
|---|---|---|---|
| BSMV on interest | 15% | None on a first home | 5% |
| BSMV on fees | 15% | None on a first home | 5% |
| KKDF on interest | 15% | None on a first home | 0% in TL |
| Stamp duty | None | None | None |
| Mortgage fee | None | None | None |
The housing exemption covers someone with no home in their name on the day the loan is paid out. A tax office ruling of 11 November 2024 says even a share in a home removes it.
Paying early
On a consumer loan other than housing there is no early repayment charge; the interest for the unpaid months is taken off (Law 6502, art. 27).
On a housing loan a charge may apply only at a fixed rate and only if the contract says so: at most 1% of the amount paid early when 36 months or less remain, 2% when more remain (art. 37). A variable rate carries no charge.
The annual cost rate
The annual cost rate includes interest, KKDF, BSMV and the fees paid up front. Banks leave insurance premiums out. On a housing loan appraisal and mortgage costs are in too.
The rate is the monthly rate at which the net amount you receive equals the present value of your instalments, made yearly. Example: 150,000 TL over 12 months at 3.59% a month. The instalment is 16,607.46 TL (with 15% KKDF and 15% BSMV on the interest). The allocation fee is 750 TL, 862.50 TL with BSMV. You receive 149,137.50 TL. The monthly rate is 4.7684%, and the annual cost rate 74.89%.
An example by loan type
Without insurance the extra costs come to about 0.6% of a personal loan and 1.3% to 1.4% of a housing loan.
| Item | Personal 100,000 TL | Vehicle 1,000,000 TL | Housing 3,000,000 TL, first home |
|---|---|---|---|
| Allocation fee | 575 TL | 5,750 TL | 15,000 TL |
| Appraisal | – | – | 20,101 TL |
| Mortgage / pledge | – | 403.56 TL | 3,600–4,800 TL |
| DASK (compulsory, yearly) | – | – | 897–3,465 TL |
| Extra cost without insurance | 575 TL | 6,154 TL | 39,598–43,366 TL |
The housing example is a 100 m² reinforced concrete flat; the DASK premium depends on the earthquake zone.
You can run this with your own figures in the Bankacı app and the member portal.
Retail loans: personal, vehicle and housing loan calculation →Housing loan calculation →Business loan calculation →Download the app ↗Member portal ↗
Frequently asked
Can a bank charge a file fee besides the allocation fee?
Not on a consumer loan. Nothing may be charged as an inquiry, file or transaction fee. For appraisal, mortgage and pledge only what is paid to others may be passed on.
Is BSMV added to the allocation fee?
Yes, 15%. The 0.5% ceiling excludes BSMV, so a 500 TL fee on 100,000 TL is paid as 575 TL. A housing loan to someone with no home in their name carries no BSMV.
Do I pay a penalty if I close my loan early?
Not on a consumer loan other than housing. On a fixed-rate housing loan, if the contract says so, at most 1% may be charged when 36 months or less remain and at most 2% when more remain.
Does the annual cost rate include insurance?
Banks leave it out. The rate is worked out from interest, taxes and fees; to compare an insured loan, add the premium yourself.
Sources
- Central Bank of the Republic of Türkiye, communiqué on fees charged to financial consumers (2020/7), with the instruction of 13.1.2026
- Central Bank of the Republic of Türkiye, communiqué on fees charged to commercial customers (2020/4), article 9, change of 18.9.2025, in force from 1.11.2025
- Law 6502 on Consumer Protection, art. 27 and art. 37, read on 12.11.2026: mevzuat.gov.tr
- Regulation on Consumer Credit Contracts, art. 4 and art. 14, Annex 1, read on 12.11.2026
- Capital Markets Board, 2026 minimum appraisal fee schedule, 1.1.2026
- Expenditure Taxes Law art. 29/1-y and Presidential Decision 7345, 7.7.2023
- Stamp Duty Law 488 (table 2, IV-23) and Fees Law 492, art. 123/2, read on 12.11.2026
This page is general information. The amounts your bank charges are in your contract and in the fee calculator on the bank's site; this page shows only the legal ceilings and examples.
Be ready for your next calculation.
Download Bankacı for free.
 Scan with your phonebankaci.app/indir