BUSINESS LOANS
Instalment, spot, revolving and discount
On the business side a loan is not one product. Bankacı calculates four of them separately, because interest behaves differently in each.
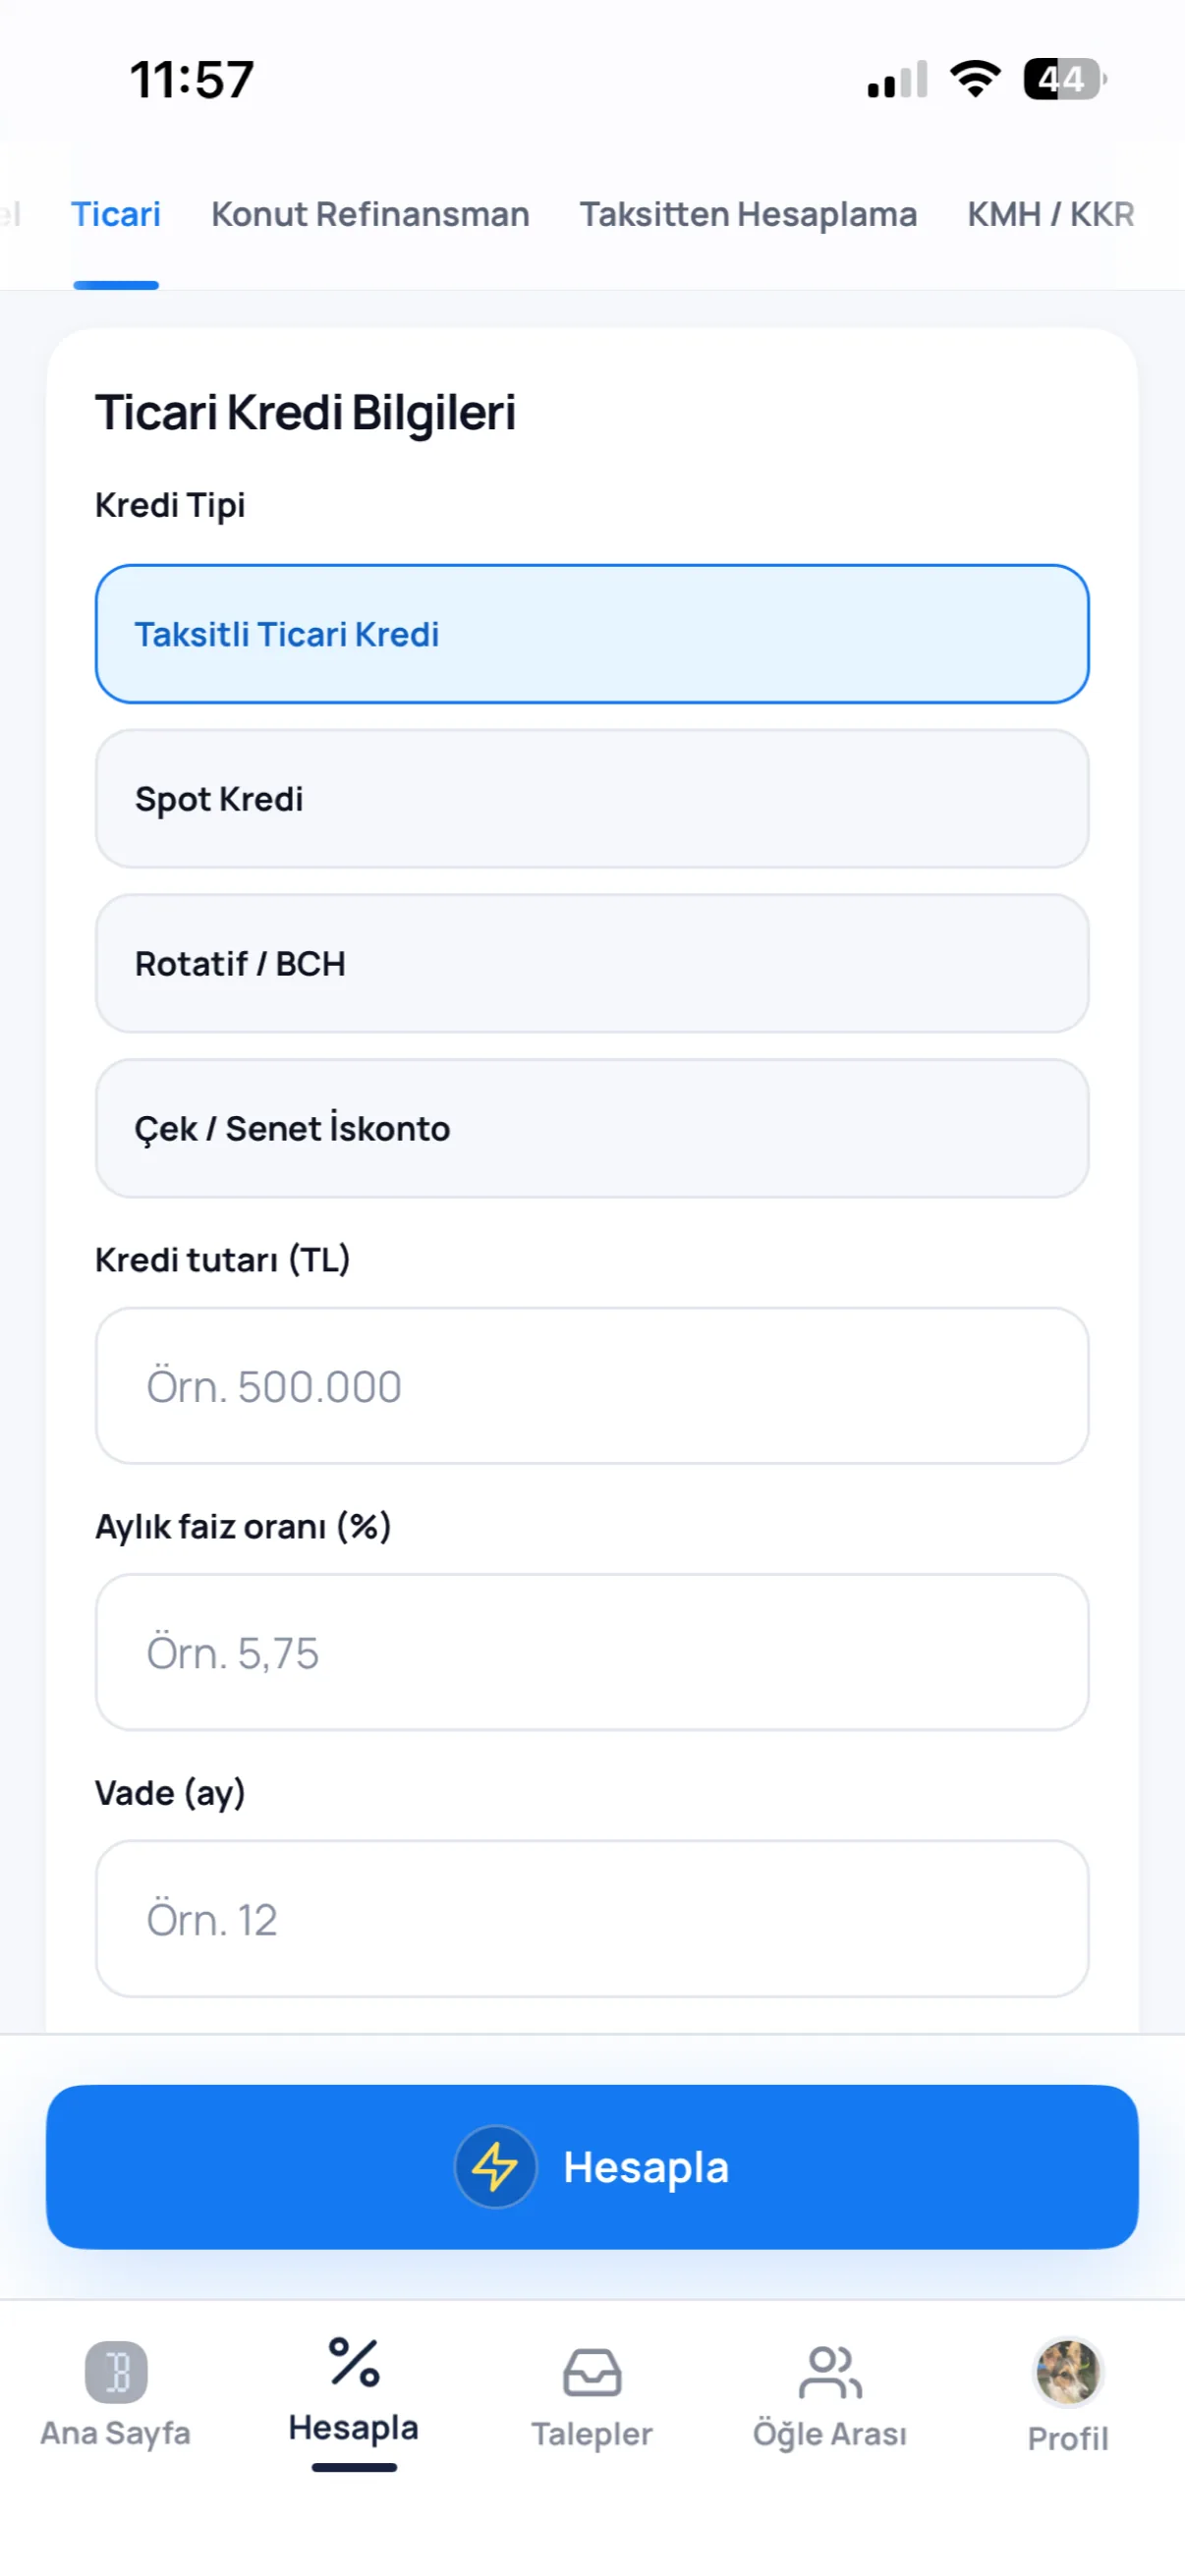
Instalment business loan
The closest to a consumer loan, except that payments need not be monthly: quarterly or semi-annual schedules are common where cash flow is seasonal. Bankacı handles all three frequencies.
Spot loan
The principal is repaid in one go at maturity while interest is collected periodically. It suits a business waiting on a specific receipt.
Revolving credit
An account drawn and repaid within a limit, where interest runs on the days used. Bankacı works it out movement by movement — each draw and each repayment carries its own day count.
Cheque and note discounting
Bringing an undated cheque or note back to present value. The result is the net amount the customer receives, commission and taxes included.
Frequently asked
Are legal limits shown on business loans?
No. Bankacı's limit tables come from Board decisions on consumer credit; there is no verified table on the business side, and an invented limit would be indistinguishable from a real one.
How does interest run on a revolving account?
Each movement is valued on its own day count, so interest follows how long a balance was actually outstanding rather than the closing balance.
Can I show a quarterly plan to the customer?
Yes, the schedule prints exactly as a monthly one does and can be shared.
See also: Instalment business loan · Spot loan calculation · Revolving credit calculation · Cheque and note discounting · Glossary
Be ready for your next calculation.
Download Bankacı for free. Start calculating in seconds.
 Scan with your phone — bankaci.app/indir